The rise of GLP-1 weight-loss drugs is transforming the global food and drink industry. For high-volume beverage brands, this shift presents both a structural challenge and a major growth opportunity.
As consumers using GLP-1 medications eat less and become more selective, demand is moving away from low-value, high-volume consumption and toward functional, nutrient-dense solutions. This is where GLP-1 beverages come into play.
For brands that act quickly, the opportunity is clear: redefine beverages as essential tools for hydration, nutrition, and wellbeing.
What are GLP-1 drugs and why do they matter for beverage brands?
GLP-1 (glucagon-like peptide-1) drugs are widely used for weight loss and appetite suppression. Their rapid adoption across the US and UK is already reshaping how consumers approach food and drink.
Consumers on GLP-1 drugs are eating fewer calories, reducing their overall food spend, and becoming more intentional in their choices. Rather than consuming out of habit or impulse, they are prioritising nutrient density and functional benefits in both food and drink. This shift is already putting pressure on traditional categories, particularly sugary and low-satiety products.
At the same time, it is accelerating demand for GLP-1 drinks, functional beverages, and hydration solutions that deliver more value in smaller formats.
Why GLP-1 beverages are a major growth opportunity

Among all categories, beverages are uniquely positioned to respond to this shift. With reduced appetite and fewer eating occasions, consumers are increasingly looking for easy-to-consume, nutritionally efficient options that fit seamlessly into their day.
Drinks offer a low-friction way to deliver protein, fibre, electrolytes or micronutrients without requiring a full meal. This makes GLP-1 beverages a powerful solution, allowing brands to move beyond simple refreshment into functional nutrition and metabolic support.
Hydration drinks for GLP-1 users
Hydration is evolving into a far more functional space. Many GLP-1 users experience dehydration, nausea, or digestive discomfort, which increases demand for drinks that actively support the body rather than simply quench thirst.
This is creating opportunities for electrolyte-enhanced beverages that improve hydration efficiency, as well as gut-friendly formulations designed to be gentle on digestion. At the same time, vitamin- and mineral-enriched drinks are gaining traction as consumers look to maintain nutritional balance despite reduced food intake. Together, these trends are driving the emergence of functional hydration drinks as a core pillar of the GLP-1 beverage market.
High-protein drinks and nutrient-dense beverages
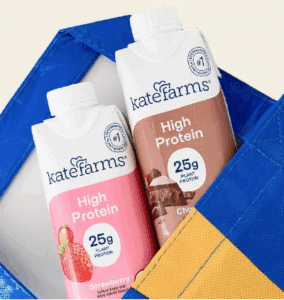

Plant based High Protein Nutrition Shakes, specifically designed to address
“critical nutrition gaps” from GLP 1 use, Kate Farms (US)
Protein has become central to the GLP-1 diet, particularly as consumers look to maintain muscle mass during weight loss. Fibre is also playing an important role in supporting satiety and digestive health.
Beverage formats are ideally suited to deliver these benefits. High-protein drinks, fibre-enriched beverages, and nutrient-dense smoothies allow brands to provide meaningful nutrition in smaller, more manageable servings. This aligns perfectly with the needs of GLP-1 consumers, who are seeking maximum nutritional impact with minimal volume. As a result, functional beverages are becoming an increasingly important part of daily consumption habits.
Smaller formats and portion-controlled drinks
GLP-1 is accelerating a broader shift towards portion control and precision consumption. Consumers are becoming less interested in large formats and more focused on products that deliver exactly what they need, without excess.
For beverage brands, this is driving demand for smaller pack sizes, concentrated nutrition formats, and premium single-serve options. The emphasis is no longer on quantity, but on efficiency and effectiveness. This shift creates an opportunity to rethink both product design and pricing strategy, positioning beverages as higher-value, purpose-driven solutions.
Moving beyond “diet drinks” to functional positioning
Traditional “diet” messaging is losing relevance in the GLP-1 era. Consumers are no longer simply trying to reduce calorie intake; they are actively trying to optimise their nutrition and overall wellbeing.
As a result, brands are shifting away from language centred on restriction and towards positioning that emphasises function and benefit. This includes focusing on metabolic support, nutrient density, and overall health outcomes. For beverage brands, this represents a critical evolution, enabling them to move from legacy diet positioning into the more future-facing space of functional beverages and GLP-1 drinks.
The rise of low- and no-alcohol alternatives
GLP-1 drugs are also influencing how consumers approach alcohol. Many users report a reduced desire to drink, which is contributing to a broader cultural shift towards moderation.
This is creating new opportunities within low- and no-alcohol categories, as well as functional social beverages that align with health-conscious lifestyles. Rather than eliminating social drinking altogether, consumers are becoming more intentional about when and what they drink. This shift opens the door for beverage brands to innovate in formats that deliver both experience and wellbeing.
From GLP-1 drinks to full nutrition ecosystems
The opportunity for beverage brands extends beyond individual products. The GLP-1 trend is driving the development of broader nutrition ecosystems, where consumers actively seek support in managing their dietary needs.

Nutrition system for GLP 1 users, developed in
partnerships with dietitians and comprising gender specific nutrition shakes,
functional boosters, and electrolyte products, Maeva (US)
This includes personalised nutrition plans, subscription-based solutions, and AI-driven tools that help guide consumption decisions. Within this landscape, beverages can play a central role as convenient, reliable sources of nutrition and hydration. By integrating into these systems, brands can move from being occasional purchases to becoming part of daily routines.
Why speed is critical in the GLP-1 beverage market
GLP-1 adoption is accelerating rapidly and is expected to reshape the food and beverage industry over the next decade. As the market evolves, early movers will be best positioned to define category norms and capture long-term loyalty.
Brands that act quickly can establish credibility, secure distribution, and build strong connections with consumers who are actively redefining their habits. In contrast, those that move too slowly risk becoming disconnected from emerging expectations and losing relevance in a rapidly changing landscape.
Conclusion: A defining moment for drink brands
GLP-1 is not a short-term trend but a fundamental shift in consumer behaviour. It is changing not only how much people consume, but also what they expect from every product they choose.
For high-volume beverage brands, this represents a defining moment. Success will depend on the ability to develop GLP-1 beverages and functional drinks that deliver real value, align with evolving health priorities, and respond quickly to changing consumer needs.
In this new landscape, beverages are no longer just about refreshment—they are becoming essential tools for hydration, nutrition, and overall wellbeing.
Act now: Unlock the GLP-1 beverages opportunity
The window to lead in the GLP-1 beverage market is now. Brands that act with speed and clarity will define the future of the category.
Chat to our experts today to find out how we can support your brand in capitalising on this opportunity. From rapid insight generation and concept development to formulation strategy and go-to-market execution, we combine deep category expertise with the speed required to help you stay ahead in a fast-moving market.